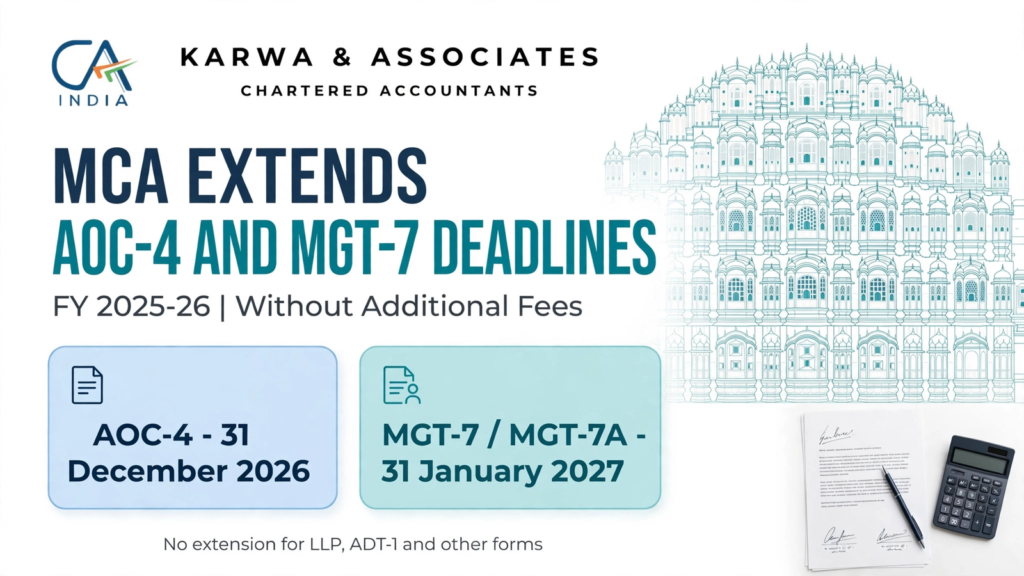
The Ministry of Corporate Affairs (MCA) has extended the due dates for annual filings for the financial year 2025-26. Under General Circular No. 05/2026 dated 24 October 2026, companies can now file their financial statements in AOC-4 and related forms up to 31 December 2026, and their annual returns in MGT-7 and MGT-7A up to 31 January 2027, without paying any additional fees. The extension does not cover the time for holding annual general meetings, and it does not cover LLP forms, ADT-1 or any other forms.
Official Circular/Document
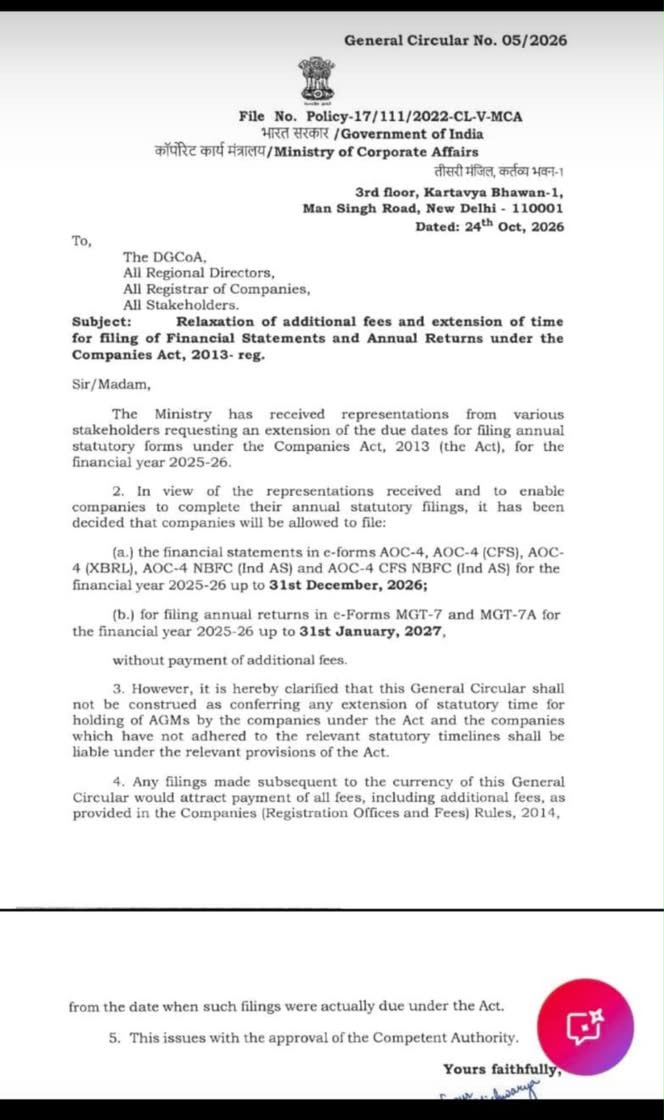
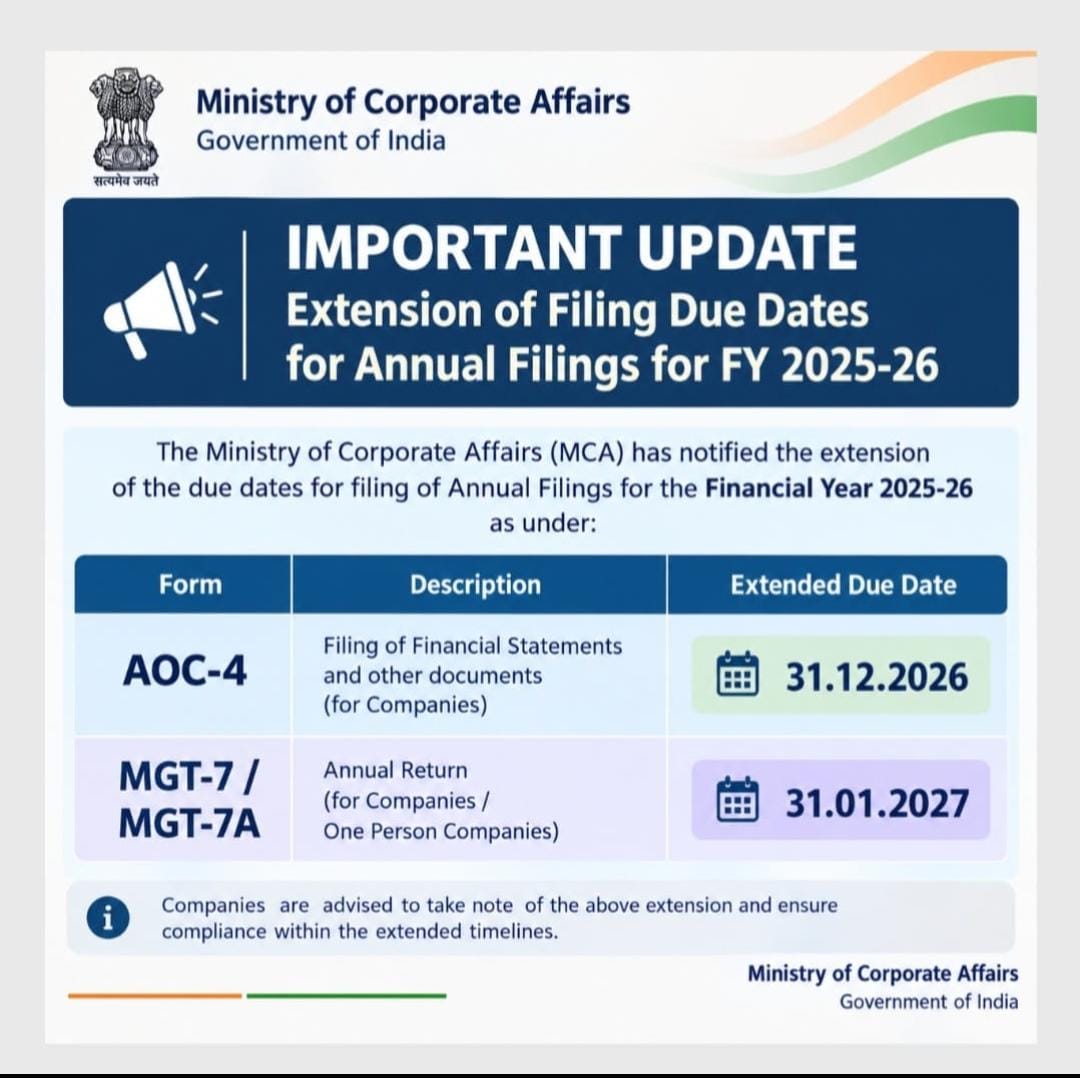
The relaxation comes from General Circular No. 05/2026 (File No. Policy-17/111/2022-CL-V-MCA), issued by the Ministry of Corporate Affairs, Government of India, on 24 October 2026. The subject of the circular is “Relaxation of additional fees and extension of time for filing of Financial Statements and Annual Returns under the Companies Act, 2013”. The circular was issued after representations from stakeholders asking for more time to complete annual statutory filings. Read the circular below, and the MCA’s own summary graphic after it.
Download the official circular (PDF)
Extended Due Dates for FY 2025-26
| Forms | What they cover | Extended due date |
|---|---|---|
| AOC-4, AOC-4 (CFS), AOC-4 (XBRL), AOC-4 NBFC (Ind AS), AOC-4 CFS NBFC (Ind AS) | Financial statements and related documents | 31 December 2026 |
| MGT-7, MGT-7A | Annual return (companies and One Person Companies) | 31 January 2027 |
Filings made within these extended dates will not attract additional fees. This is a genuine relief for companies still finalising their accounts and annual return data after the annual general meeting season.
What Is NOT Covered: LLP, ADT-1 and Other Forms
The circular extends only the forms it names. It gives no extension for:
- LLP forms, including the annual statement of account and solvency and the annual return of an LLP
- ADT-1, the form for appointment of auditors
- Any other MCA form outside the AOC-4 and MGT-7 families
For all of these, the original statutory due dates continue to apply, and additional fees will run as usual from those dates. Do not assume that the MCA relief covers your LLP or auditor appointment filing. If any of these filings are pending, treat them as urgent and file them on the original timeline.
AGM Timeline Is Not Extended
The circular states this in clear terms: it does not extend the statutory time for holding annual general meetings. A company must still hold its AGM within the timeline prescribed by the Companies Act, 2013. The extension applies only to the filing of the financial statements and the annual return after the AGM. Companies which have not adhered to the statutory AGM timelines remain liable under the Act, even though their filing dates are extended.
What Happens If You Miss Even the Extended Date
The circular also carries a warning worth reading carefully. Filings made after the currency of this circular will attract all fees, including additional fees, under the Companies (Registration Offices and Fees) Rules, 2014, calculated from the date the filing was actually due under the Act. In plain terms: if you miss 31 December 2026 for AOC-4 or 31 January 2027 for MGT-7, the additional fee clock runs from the original due date, not from the extended date. The relief is real, but it has a hard end: miss the extended date and the relief is lost, with additional fees running from the original due date exactly as if the extension had never applied.
What Companies Should Do Now
- Hold the AGM on time. The extension does not buy you AGM time, so fix the AGM date first.
- Finalise and adopt the financial statements, then file the applicable AOC-4 form by 31 December 2026.
- File MGT-7 (or MGT-7A for a One Person Company) by 31 January 2027, using the AGM date and the adopted financials.
- Separately clear any pending LLP filings, ADT-1 and other forms on their original due dates. Do not let them ride on this circular.
- Use the extra weeks to get the filings right rather than to start late. A filing made within the extended window costs no additional fee, but a filing made after it costs additional fees from the original due date.
Frequently Asked Questions
Which MCA forms are extended for FY 2025-26?
The AOC-4 family (AOC-4, AOC-4 CFS, AOC-4 XBRL, AOC-4 NBFC Ind AS and AOC-4 CFS NBFC Ind AS) up to 31 December 2026, and MGT-7 and MGT-7A up to 31 January 2027, all without additional fees.
Is the AGM date also extended?
No. General Circular No. 05/2026 expressly does not extend the statutory time for holding annual general meetings. Only the filing dates are extended.
Does the extension apply to LLPs and ADT-1?
No. LLP forms and ADT-1 are not named in the circular, so they get no extension. Their original due dates and additional fee rules continue to apply.
What if I file after the extended date?
Additional fees will apply under the Companies (Registration Offices and Fees) Rules, 2014, calculated from the date the filing was actually due under the Act, not from the extended date.
About the Author
Written and reviewed by CA Anshul Karwa, Chartered Accountant (DISA-qualified) associated with Karwa & Associates, Chartered Accountants, Jaipur. The firm advises companies on MCA annual compliance, audits, tax and advisory matters. This post is for general information only and is not a substitute for professional advice on your specific facts.
CA Anshul Karwa is a Chartered Accountant (DISA-qualified) and Partner at Karwa & Associates, Chartered Accountants, Jaipur. A non-commerce student who cleared CA in the first attempt, he worked with Big 4 firms and MNCs before joining the firm. He also builds digital apps, websites and tools for CAs, founders and other professionals, and writes books on investing.